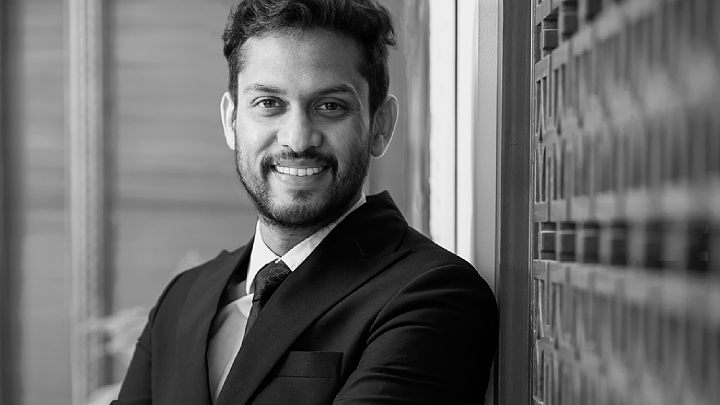
'We See Considerable Real Estate Opportunity In Delhi-NCR On New Infra, Urban Planning': Omaxe MD Mohit Goel
India’s real estate market is witnessing a shift towards premium housing, integrated townships and mixed-use developments, with infrastructure expansion reshaping growth opportunities across Delhi-NCR and emerging cities
By Mohammad Haris··39K reads
'We See Considerable Real Estate Opportunity In Delhi-NCR On New Infra, Urban Planning': Omaxe MD Mohit Goel
India’s real estate market is witnessing a shift towards premium housing, integrated townships and mixed-use developments, with infrastructure expansion reshaping growth opportunities across Delhi-NCR and emerging cities. In an interview with news18.com, Mohit Goel, managing director of Omaxe Ltd, discusses evolving homebuyer preferences, the potential of Delhi Master Plan 2047, rising NRI interest, hospitality opportunities in Tier-II cities and the company’s execution priorities over the next 12-18 months. Edited excerpts:
How do you assess the current real estate market in India, particularly Delhi-NCR?
The Indian real estate market is entering a more mature phase of growth, with Delhi-NCR particularly well placed because of its expanding infrastructure, employment base and commercial activity. The region is benefiting from major connectivity projects such as the Dwarka Expressway, Jewar airport and continuing metro expansion, which are opening up new residential and commercial growth corridors.
The recently notified Delhi Master Plan 2047 adds another important dimension. Delhi-NCR also recorded 15.8 million sq ft of office leasing in 2025, up 24% from the previous year. This connection between employment, commercial activity and housing demand gives us confidence in the region’s long-term prospects.
The ongoing festive season should further support enquiries and conversions, particularly in well-connected premium and mid-premium developments. We see considerable opportunity as new infrastructure and urban planning open up the next generation of growth corridors across NCR.
Premium and luxury housing are gaining a larger share of new launches. What does this growing demand reveal about evolving buyer preferences, and how is it shaping the next generation of residential developments in India?
The growth of premium housing reflects a deeper change in the Indian homebuyer. People are no longer buying only for shelter or even for location. They are looking for better space, privacy, design, wellness, convenience and a stronger quality of life. This is now a structural shift.
Homes priced above Rs 1 crore accounted for 63% of residential sales in 2025, compared with 53% in 2024. The next generation of residential projects will therefore be judged by the quality of the entire living environment. Premium housing is increasingly about thoughtful planning, open spaces, connectivity and a sense of community, rather than simply a higher price tag. We see this in the demand for larger, better-planned homes across our markets.
How do you see Delhi Master Plan 2047 creating new opportunities for residential real estate and strengthening Delhi-NCR’s growth story?
Delhi Master Plan 2047 can reshape the way the capital grows over the coming decades. The important opportunity is not simply the creation of more housing. It is the possibility of bringing land, infrastructure, mobility and development into a more coordinated framework.
The plan envisages around 40 lakh new homes and gives greater attention to redevelopment, transit-oriented development and land pooling. This can unlock new residential opportunities while strengthening Delhi’s relationship with the wider NCR.
Connectivity and planned infrastructure can support larger urban destinations. The real test will be implementation. If infrastructure keeps pace with development, MPD 2047 can help Delhi accommodate growth while creating more connected and liveable neighbourhoods.
Why are emerging growth corridors and transit-oriented development becoming the new definition of integrated townships, and what is driving this shift in buyer preferences?
The meaning of location is changing in Indian real estate. Earlier, buyers primarily looked at the project and its immediate surroundings. Today, they increasingly consider the larger ecosystem around it. Access to metro networks, highways, airports, employment centres, schools, healthcare, retail and leisure can determine how a location develops over time.
This is where growth corridors and transit-oriented development become important. Buyers want less commuting and more convenience. Integrated townships are therefore evolving into complete neighbourhoods where connectivity and planning work together to create lasting urban value.
NRI interest in Indian real estate is growing beyond emotional ties. What makes India increasingly attractive as a long-term investment destination for NRIs?
The NRI relationship with Indian real estate has become much more investment-oriented. Emotional attachment remains important, but the decision today is increasingly based on India’s economic growth, urbanisation, infrastructure development and the improving quality of organised real estate.
The depth of institutional confidence is also encouraging. India’s real estate sector attracted a record US$10.5 billion in institutional investment in 2025, with domestic institutions accounting for 52% of the total for the first time since 2014. For NRIs, this is important because it reflects a more mature and credible market.
India’s urbanisation story is still unfolding, creating opportunities across established cities and emerging growth centres. We see this preference for quality, established locations and differentiated developments across our markets. For NRIs, Indian property is increasingly a long-term wealth-creation and diversification opportunity, alongside its traditional connection to home.
How is the growing focus on mixed-use development changing the way cities are planned and how people experience urban living?
Mixed-use development reflects a more practical understanding of how people want to live. Separating homes, workplaces, retail, hospitality and leisure creates longer journeys and places greater pressure on urban infrastructure. Bringing these uses together can create more active and convenient neighbourhoods, provided they are planned properly.
The Omaxe State in Dwarka is an example of this approach, bringing sports, retail, food, hospitality and social uses together across a 50.4-acre destination. It includes a 30,000-seat cricket and football stadium, a 2,000-capacity indoor stadium and extensive retail and food spaces.
The larger idea is important. Mixed-use development is moving beyond putting different asset classes together. It is about creating destinations where people can spend time, work, shop, socialise and access entertainment within one connected environment.
What factors do you believe are driving the growing hospitality opportunity in Tier-II cities markets?
The hospitality opportunity in Tier-II cities is being driven by a much broader demand base than we saw in the past. Domestic tourism, pilgrimage, weddings, business travel, meetings, incentives, conferences and exhibitions (MICE) activity, and improving connectivity are all contributing to demand.
The numbers reflect this broader shift. In 2025, hotel brands signed around 64,118 rooms across 586 properties, with development extending into newer markets across the country. National hotel occupancy also reached around 63-65%, with average room rates of about Rs 8,500-8,700, showing that demand is supporting both occupancy and pricing.
Cities such as Ayodhya, Vrindavan and Lucknow are particularly interesting because tourism and economic activity are developing together.
Investors are increasingly focused on execution and profitability rather than just sales volume…
The real measure of a real estate company is its ability to convert its development pipeline into completed projects, collections and sustainable profitability. That is where our focus needs to remain. Omaxe delivered 4.29 million sq ft in FY25, taking its cumulative delivered area to 140.17 million sq ft, with annual deliveries increasing 11.7%. The next phase is about maintaining that execution momentum while improving cash generation and project-level economics.
Over the next 12-18 months, the market should watch construction progress, deliveries, collections, project profitability and the trajectory of debt and finance costs. Our objective is not simply higher sales. It is to create a more predictable business where project execution, cash flows and profitability reinforce each other.