Jio Platforms IPO Listing: Analysts See Long-Term Growth Potential, Initiate Coverage With 'Buy' Calls
Jio Platforms IPO Listing: Jio Platforms Ltd made a strong debut on the Indian stock market on Wednesday, October 28, with its shares listing at Rs 1,358 apiece on both the BSE and NSE, a premium of 21.36% over the initi
By Business Desk··25K reads
Jio Platforms IPO Listing: Analysts See Long-Term Growth Potential, Initiate Coverage With 'Buy' Calls
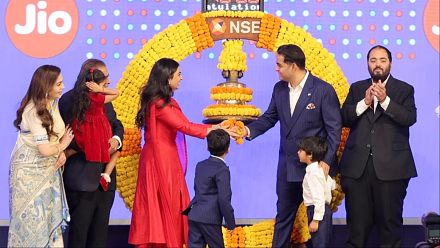
Jio Platforms IPO Listing: Jio Platforms Ltd made a strong debut on the Indian stock market on Wednesday, October 28, with its shares listing at Rs 1,358 apiece on both the BSE and NSE, a premium of 21.36% over the initial public offering (IPO) price of Rs 1,119. The listing has brought the Reliance Industries-backed digital services company into the spotlight, with brokerages highlighting its telecom leadership, digital expansion opportunities and potential for long-term value creation.
Brokerages Motilal Oswal Financial Services, Nomura and Elara Capital initiated coverage on Jio Platforms with ‘Buy’ recommendations, citing growth opportunities across mobile connectivity, home broadband and digital services.
While Motilal Oswal has set a base-case target price of Rs 1,350 per share, Nomura has assigned a target of Rs 1,340, and Elara Capital has a target price of Rs 1,367 per share.
The brokerage calls come as investors assess the company’s prospects following its Rs 30,213-crore IPO, one of the most closely watched public offerings in India’s capital market.
Ravi Singh, Chief Research Officer at Master Capital Services Ltd, said, “The company, incorporated on 15 November 2019, is a technology platform built on proprietary digital technology and pan-India digital connectivity, driving digital transformation across India. It offers a broad portfolio of consumer and enterprise services, including mobile and fixed broadband, digital entertainment, cloud and productivity solutions, IoT, cybersecurity, managed services and AI applications. Its distribution ecosystem combines digital channels, such as the MyJio App, with physical access points, supported by Reliance Retail Limited for prepaid connectivity distribution, marketing and customer acquisition.”
He added that digital entertainment is expected to grow from Rs 562 billion to Rs 920 billion at a CAGR of 10%. Personal digital productivity solutions are expected to grow from Rs 160 billion to Rs 482 billion at a CAGR of 25%.
Motilal Oswal Initiates Coverage With Buy Rating
Motilal Oswal Financial Services has initiated coverage on Jio Platforms with a ‘Buy’ recommendation and a base-case target price of Rs 1,350 per share.
The target price implies an upside of approximately 20.7% over the IPO issue price of Rs 1,119. However, it is marginally below the stock’s listing price of Rs 1,358.
The brokerage’s initiation puts the focus on Jio Platforms’ long-term growth prospects and valuation as the company begins its journey as a publicly traded stock.
Investors will need to assess the target price against the prevailing market price, as the potential return from the listing price may differ from the upside calculated using the IPO issue price.
Nomura Sees 13.5% EBITDA CAGR, Cites Telecom Leadership
Global brokerage Nomura has initiated coverage on Jio Platforms with a ‘Buy’ rating and a target price of Rs 1,340 per share.
The brokerage highlighted Jio’s position in India’s telecom market, the growth potential of home broadband and the prospect of improving free cash flow as key elements of its investment thesis.
“Jio, once the disruptor, is now the leader,” Nomura said.
According to the brokerage, Jio accounts for 42% of India’s wireless subscribers, 60% of data traffic and 43% of home broadband.
Nomura expects Jio Platforms’ earnings before interest, taxes, depreciation and amortisation (EBITDA) to grow at a CAGR of 13.5% between FY2026 and FY2029.
The brokerage believes the company’s position in the telecom market could support further tariff increases, with competitors potentially following its pricing moves.
Home broadband is another potential growth driver, supported by Jio’s network infrastructure and customer reach.
Nomura also expects capital expenditure intensity to decline as much of the 5G investment cycle moves into the rear-view mirror. Lower capital expenditure intensity, alongside earnings growth, could support a substantial improvement in free cash flow.
“Strong network + largest subscriber market share = long-term value creation,” Nomura said.
The brokerage’s assessment suggests that Jio Platforms’ future performance will depend not only on subscriber growth but also on its ability to improve monetisation, manage investment requirements and translate operating earnings into cash flow.
Elara Capital Sets Rs 1,367 Target Price
Elara Capital has also initiated coverage on Jio Platforms with a ‘Buy’ recommendation, setting a target price of Rs 1,367 per share.
The brokerage has valued the company at 11.5 times its estimated FY2029 enterprise value-to-EBITDA (EV/EBITDA) ratio, reflecting its assessment of Jio Platforms’ future earnings potential.
Elara Capital’s investment thesis centres on the company’s transition from a traditional telecom operator towards a broader digital platform.
The brokerage sees opportunities to monetise Jio’s extensive customer base and technology infrastructure through an expanding range of digital services.
The strategy could allow the company to generate additional revenue from its existing ecosystem, although the extent of monetisation will depend on customer adoption, pricing, competition and execution.
Elara Capital’s target price is an estimate of the stock’s potential value, not a guaranteed return. Investors should also consider the valuation implied by the market price following the listing.
Disclaimer: News18 is part of the Network18 group. Network18 is controlled by Independent Media Trust, of which Reliance Industries is the sole beneficiary.